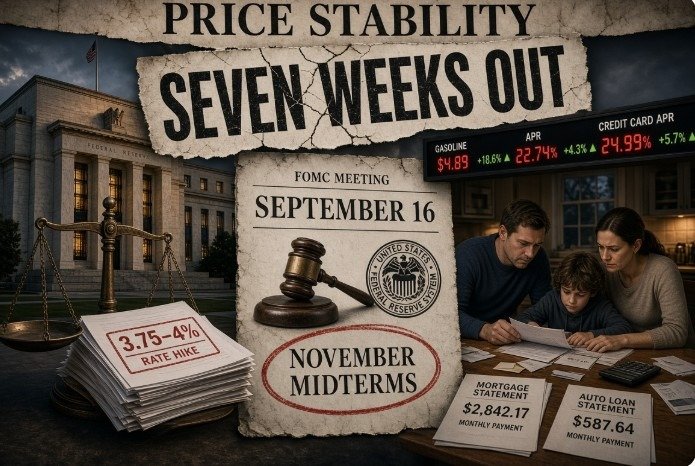
WASHINGTON — The Federal Open Market Committee raised the federal funds target by a quarter point today to a range of 3.75 to 4 percent — the first hike since July 2023 — and did it seven weeks before the midterms.
That is not a weather report. It is a political calendar. Households feel this in mortgages, auto notes, credit cards, and small-business lines. The Committee said inflation remains elevated and that the move would support a “timelier” return to 2 percent. Fine. Then say the other sentence out loud: the same institution that spent years lecturing the country about independence just tightened credit in the last stretch of an election defined by affordability.
President Trump spent months demanding cuts — even calling for rates near 1 percent. His own chair, Kevin Warsh, voted with a unanimous 12–0 board to go the other way and signaled another hike is on the table before year-end. Inflation is real. Energy spiked with the Iran fight. Productivity and investment are still running. None of that erases the timing. White House economic officials themselves warned that a hike this close to November would look like the Fed stepping into the campaign. They hiked anyway.
Call it independence if you must. Voters will call it a thumb on the scale. An antiquated central bank that answers to its own priesthood, not to the people who pay the note, is overdue for a revamp — mandate, appointments, and the habit of moving the goalposts when the names on the ballot change. FAAFO is not a slogan for a press conference. It is what happens when an unelected shop tightens the vise and then hides behind “price stability.”
The economy does not pause for FOMC choreography. Neither will November.
— Josiah Hale, WAA1776
References